How to Use Constants as a Loan Officer
Loan officers already have a licensed process for getting someone from a raised hand to a closed loan: a pre-approval call, a set of documents to walk through, and a rate that changes with the market every day. What most loan officers don't have is one place to send someone who just found their Instagram post — everything after that first click still lives across a Calendly link, a PDF emailed on request, and a Facebook group for past clients.
A page that leads with what borrowers actually check first
Your license number, the states you're licensed in, a headshot, and a way to reach you — that's what a borrower is looking for before they'll even consider booking a call. A landing page puts all of it above the fold instead of buried in an email signature, and it's the same page for every campaign you run instead of a new link for every ad.
Book the pre-approval call directly
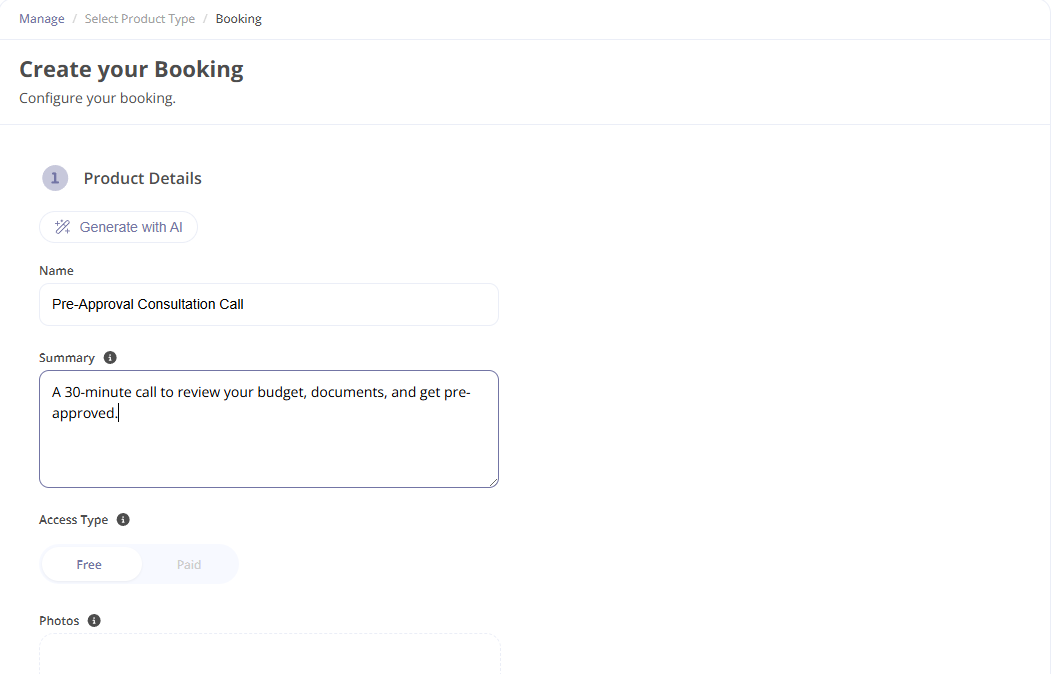
A borrower who's ready doesn't want to wait for a callback. 1:1 Bookings gives them a real calendar to grab a slot on directly — a rate consultation, a pre-approval call, a first-time buyer strategy session — the moment they're motivated, instead of leaving a voicemail that turns into a week of phone tag. It's the same booking mechanic used to sell coaching sessions, just applied to a licensed process instead of a training program.
Turn a homebuyer seminar into something people register for
A first-time homebuyer workshop or a rate-market update isn't a flyer, it's an event with a start time and a headcount. Constants' Events tool handles the sign-up directly, so a seminar becomes something people commit to attending instead of something they meant to show up for and forgot by Thursday.
Sell the guide you already explain on every call
Every loan officer already has an explanation they give on repeat — down payment assistance programs in their state, how closing costs actually break down, what moves a credit score before underwriting even starts. As a digital product, that explanation becomes a guide someone can download from the page directly, instead of something you retype in a follow-up email every time a new lead asks the same question.
Let the agent handle the process questions
Most of what a borrower asks before ever booking a call is the same handful of questions: what's the process, what documents do you need, are you licensed in my state. An Agent trained on your process and licensing can answer those the moment someone lands on the page, and point them at booking a call for everything that actually has to come from you — it's built to handle the process questions, not to quote a rate or give advice that requires your license.
See which page borrowers actually act on
Analytics shows page views alongside clicks per link, so instead of guessing which offer to lead with in your next campaign, you can see directly whether people click your booking link, your guide, or your seminar sign-up more — and put the one that's actually working at the top of the page.
What it actually costs
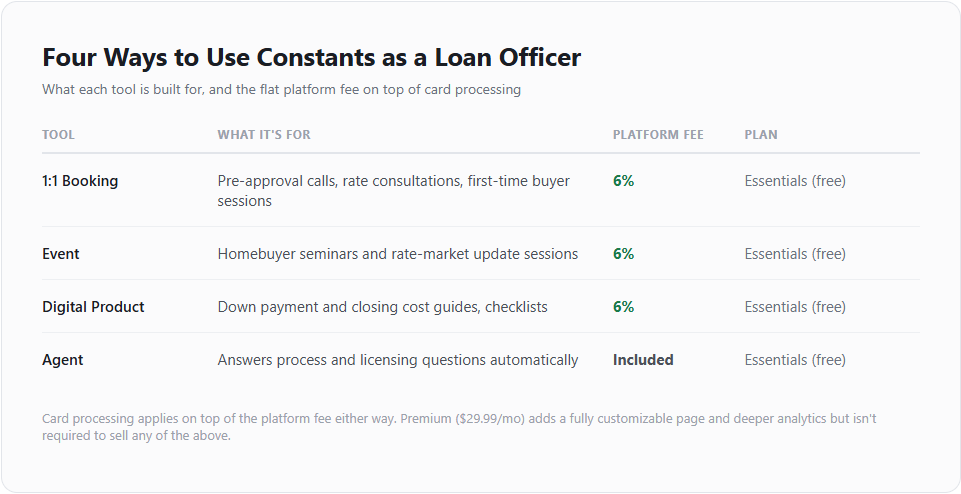
The Essentials plan is free, and everything above works on it from day one. Digital products, bookings, and events carry a flat 6% fee on the sale; memberships run 10%, in the same range most subscription tools charge for recurring billing. Card processing applies either way. Premium is $29.99/mo for a fully customizable page and deeper analytics, but nothing above requires it to get started — the full breakdown is on the pricing page. Whatever you post on the page still has to follow your own license's advertising rules; the platform doesn't change that.
One page instead of a Calendly link, a PDF, and a Facebook group
Most loan officers end up with the pre-approval call booked through one tool, the guide emailed out by hand, and a Facebook group for past clients that nobody else can find. A single page that books the call, sells the guide, and runs the seminar turns three disconnected habits into the one place you can see what a borrower actually did before they called you — the same structure that works for a fitness coaching business, just built around a licensed process instead of a training program.